How to Pay for Rehab: A Clear Financial Guide for 2026
Reviewed by Tiffany Komba, LMFT (State of California LMFT #136055) on November 14, 2026
Published June 23, 2026 · Updated June 25, 2026
Contents
- Facing the Cost of Recovery Is Your First Step
- Using Your Insurance to Cover Rehab Costs
- Public Benefits and Veteran Options for Treatment
- Navigating Self-Pay and Facility Payment Plans
- Bridging the Gap with Loans and Financial Aid
- Your Pre-Intake Financial Checklist
- Take the Next Step with Addiction Resource Center
You may be staring at a rehab estimate, your insurance card, and your bank app all at once, thinking a common thought in that moment: We're finally ready to get help, but how are we supposed to pay for it?
That stress is real. It hits families in Yuba City, Sacramento, Chico, and across Northern California every day. Someone is ready for detox, residential treatment, or IOP, and the money question lands like a door slamming shut.
It isn't a shut door.
Paying for treatment is usually a mix of options, not one magic answer. Insurance may cover part of it. A facility may offer a payment plan. Some people use savings for admission and finance the rest in a structured way. Some need to protect their job, housing, or credit while they get care. If debt is already part of the picture, practical expert advice on addiction and debt can help you think clearly before making rushed financial decisions.
You don't need to solve every financial detail before making the first call. You need a plan for the first few steps.
Facing the Cost of Recovery Is Your First Step
The money conversation feels awful because it arrives at the exact moment you're already exhausted. Maybe your loved one just agreed to treatment after months of chaos. Maybe you've been hiding withdrawals, drinking, pills, or cravings long enough and know you can't keep doing it. Then the practical question shows up: what will this cost today, this week, this month?
That question doesn't mean treatment is out of reach. It means you're at the first real step.
People often assume there are only two lanes. Either insurance pays, or they can't go. That's wrong. Real admissions work rarely looks that simple. It usually involves verifying benefits, checking public eligibility, asking the center what they accept, and figuring out whether the remaining balance can be handled through savings, family help, financing, or a written payment plan.
Cost is a treatment-planning issue, not a moral issue. Handle it like a problem to solve, not a reason to quit.
If you're in Northern California, you also have a local advantage. You can ask direct questions, compare levels of care, and work through options with a nearby treatment team instead of trying to decode everything alone on national directories and generic websites.
A good financial plan for rehab does four things:
- Identifies the fastest path to admission. Waiting for the perfect answer often delays care.
- Protects essentials. Rent, transportation, child care, and food still matter while treatment starts.
- Avoids reckless debt. Desperation pushes people toward bad credit decisions.
- Leaves room for aftercare. Recovery doesn't end at discharge.
If you're trying to figure out how to pay for rehab, don't start with fear. Start with paperwork, questions, and priorities. That's how the process gets manageable.
Using Your Insurance to Cover Rehab Costs
A Northern California family often reaches the same moment. Someone is ready for help, the phone is in your hand, and the biggest question is whether insurance will get the person through the door. Start there. Private insurance is usually the fastest funding path to admission, but only if you verify the details before you commit to a program.
The Affordable Care Act and federal parity rules changed the baseline. Substance use treatment is treated as a covered behavioral health service in many private plans, which means detox, residential care, outpatient treatment, therapy, and medication support may be covered depending on the policy and medical review. The problem is not whether coverage exists in theory. The problem is whether your specific plan covers the specific level of care your clinical assessment recommends, at the facility you want, with the authorization the insurer requires.
Start with a real benefits verification
Call the number on the back of the insurance card and ask for behavioral health or substance use disorder benefits. If you are helping a spouse, adult child, or parent, keep the policyholder close by. That saves time if the insurer wants consent before discussing benefits.
Do not ask, "Do you cover rehab?" That question gets you a vague answer and vague answers create expensive mistakes.
Ask about the exact service being considered:
- Medical detox
- Residential treatment
- Partial hospitalization
- Intensive outpatient
- Individual therapy and psychiatric care
Intake coordinators do this every day. They know where insurance answers are often incomplete, and they can usually spot red flags before admission day.
Focus on the terms that decide your out-of-pocket cost
Insurance jargon feels bigger than it is. For rehab, it usually comes down to a few numbers and a few approval rules.
Two items drive surprise bills more than anything else. Network status and preauthorization.
A plan may cover residential treatment, but only at in-network facilities. A plan may cover detox, but only after clinical review. A plan may cover ongoing treatment, but only for a limited number of days before another review is required. Those details matter more than a customer service rep saying, "Yes, treatment is covered."
Use this call script and write everything down
Open your notes app before you call. Get the representative's name, the date, and a reference number for the conversation.
Ask these questions in this order:
- Do I have substance use disorder benefits?
- Which levels of care are covered under my plan?
- Do I need preauthorization for detox, residential, PHP, or IOP?
- What is my deductible, and how much has been met?
- What is my out-of-pocket maximum, and how much has been met?
- Do I have out-of-network benefits, or only in-network?
- Are there visit limits, day limits, or medical-necessity reviews?
- Can you send a written summary through email or my member portal?
Treat verbal reassurance as a starting point, not a final answer.
PPO, HMO, and denied claims
PPO plans usually give you more provider choice. HMO plans usually have tighter rules, and you may need referrals or stricter in-network use. That does not mean an HMO blocks treatment. It means the paperwork matters more, and delays often happen when families skip the referral or authorization step.
If a claim is denied, ask why in writing. Then ask the treatment center whether they will submit additional clinical documentation or request a peer-to-peer review. Many denials are about missing authorization, level-of-care disputes, or incomplete records. Those problems can often be addressed.
If military service, disability income, or veteran Social Security benefits are part of your household finances, mention that during intake. It may not change private insurance coverage, but it can affect how the remaining balance is handled and what proof of income you should gather before admission.
A good insurance call gives you four things. Covered levels of care, network status, authorization requirements, and a realistic estimate of your share. Once you have those, the next financial decision gets much easier.
Public Benefits and Veteran Options for Treatment
If private insurance fell through, coverage lapsed, or the deductible feels impossible, treatment may still be within reach. Start with the coverage that can be verified fastest. The right question is not "What options exist?" The right question is "Which benefit can help this admission move today?"
VA and TRICARE options
Veterans and military families should bring up VA benefits and TRICARE on the first call. Do it early. These cases often stall because nobody asks the right questions until the admission date is already slipping.
Ask the facility whether they work with TRICARE or coordinate with the VA. Then ask what is needed to keep the process moving, such as a referral, prior authorization, community care approval, or military insurance verification. Detox, residential care, and outpatient treatment may be handled differently, so get specific.
Keep these items ready for the financial conversation:
- Military insurance information
- Any referral or authorization paperwork
- A list of current medications and recent treatment history
- Income details and related supports, including veteran Social Security benefits, if they affect how the household manages time away from work or ongoing bills
Around Yuba City and the surrounding region, military families often lose time trying to sort out eligibility on their own. Do not do that. Start the benefits check and the admission process on the same day. That is how you avoid preventable delays and get a clear answer faster.
Navigating Self-Pay and Facility Payment Plans
Self-pay is common. It's not ideal for everyone, but it's normal, and many treatment centers are used to discussing it directly.
That's exactly why installment plans, sliding-scale fees, and public funding options matter in real admissions decisions, as shown in SAMHSA's N-SSATS data and cost discussion.
What self-pay really looks like
Self-pay does not always mean showing up with the full bill in one payment.
In practice, it can mean any of these:
- A cash rate for a defined service window
- An admission deposit plus scheduled payments
- A sliding-scale arrangement based on income
- A temporary self-pay plan while insurance or public benefits are being sorted out
The mistake people make is accepting the first number as final. Ask whether there is a private-pay rate, whether a longer payment schedule is possible, and whether any part of the cost changes if the level of care changes.
Questions that lead to better payment terms
When you talk to an intake coordinator or billing contact, ask direct questions that force specifics.
- What is the total expected cost for the recommended level of care? You need the estimated full picture, not just admission day.
- What is due before admission? Some families can manage a deposit even when they can't manage the full amount.
- Do you offer a written payment plan? If the answer is yes, ask for dates, amounts, and what happens if a payment is late.
- Do you offer sliding-scale fees? If income has dropped, say so plainly.
- Can you separate clinical recommendations from payment timing? You need to know what care is needed even if funding is still being arranged.
A short comparison helps:
Get everything in writing. If a center offers flexible terms verbally but won't document them, treat that as a warning sign.
You're not being difficult by asking financial questions. You're being responsible.
Bridging the Gap with Loans and Financial Aid
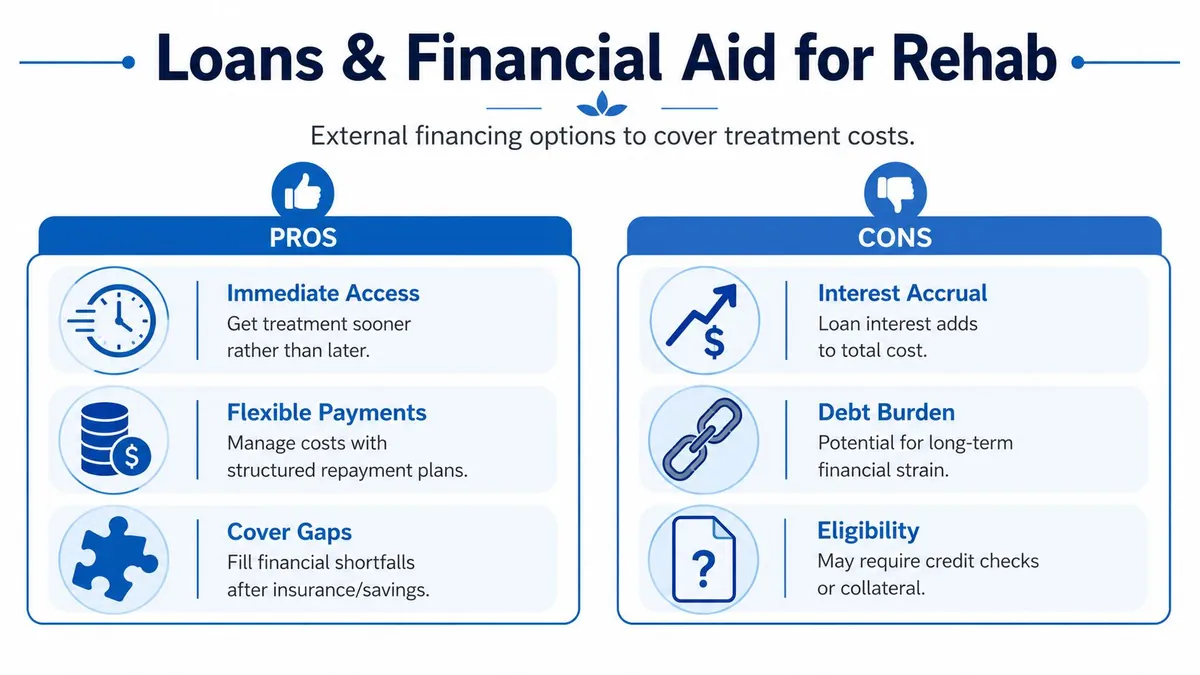
Sometimes insurance covers part, savings cover part, and there's still a gap. That's where financing can help, but only if it's structured. Bad financing creates a second crisis right after the first one starts improving.
Compare the main funding choices
Not all borrowed money behaves the same way. Treat each option differently.
A smart plan often layers sources. A structured self-pay workflow recommends combining multiple tools, such as personal savings and a fixed-term healthcare loan, instead of forcing one source to carry the whole load.
The debt mistake to avoid
The worst move is usually panic swiping multiple unsecured credit cards and hoping you'll solve it later.
That's a brutal outcome. It means the way you finance treatment can affect whether you stay in treatment.
Borrow for treatment only if the repayment plan is clear before admission. If the plan depends on "we'll figure it out later," it's not a plan.
If you use loans or credit, keep these rules in mind:
- Use fixed terms when possible. Predictable payments beat revolving uncertainty.
- Leave some cash untouched. Discharge day still brings transportation, medications, therapy, and daily life.
- Budget for aftercare. Recovery support after treatment shouldn't be an afterthought.
- Ask the facility whether outside financing can be coordinated with a payment schedule.
For people figuring out how to pay for rehab, financing should be a bridge. It should never become a trap.
Your Pre-Intake Financial Checklist
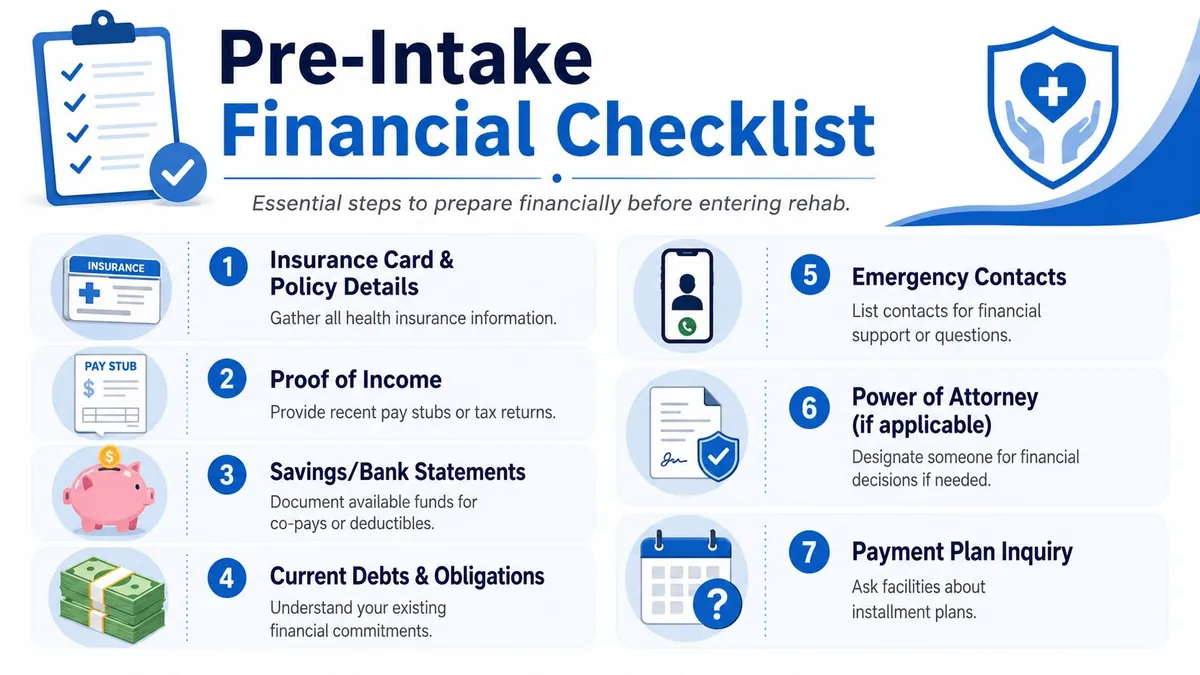
Most financial panic comes from disorganization. People call a treatment center while hunting for an insurance card, trying to remember income details, and arguing with a spouse about what they can afford. You can lower the stress fast by preparing before the intake call.
Use this checklist before you contact a center:
What to gather before you call
Put these items in one folder, paper or digital.
- Insurance card and member details Front and back. Include the subscriber name and date of birth.
- Photo ID A license or other government ID speeds up basic verification.
- Proof of income Recent pay stubs, benefit statements, or tax documents can matter for sliding-scale reviews or public applications.
- Basic bank and savings picture You don't need a spreadsheet worthy of an accountant. You do need to know what cash is realistically available.
- List of monthly obligations Rent or mortgage, car payment, child care, utilities, phone, and minimum debt payments.
- Employment information Know whether you have sick leave, PTO, HR contacts, or any flexibility to attend treatment.
- Emergency contact list Include the person who can help with logistics, money questions, or paperwork if you're admitted quickly.
- Power of attorney or decision-maker documents, if relevant This matters if someone else may need to assist with financial decisions.
What to ask during intake
Don't end the call without asking the money questions clearly.
- What will you verify for me?
- What is the expected patient responsibility at admission?
- What payment methods do you accept?
- Do you offer payment plans or sliding-scale options?
- What documents should I send today?
- If I need financing, how long do I have before admission?
- What happens if my coverage changes during treatment?
If you're considering outside borrowing, review the lender carefully before you sign anything. A practical way to start is to evaluate Tripoint Lending personal loans or any similar product with the same skepticism you'd use for any major financial decision. Look at repayment structure, fees, and whether the loan fits your budget.
Bring order to the call, and the call gets shorter, clearer, and more useful.
A prepared intake conversation doesn't just save time. It gives you a strategic advantage. You ask better questions, catch problems earlier, and make decisions with your eyes open.
Take the Next Step with Addiction Resource Center
The money side of treatment feels heavy because it touches everything at once. Health, work, family, housing, pride, and fear all show up in the same conversation. But there is a path through it.
The practical path is simple. Verify insurance if you have it. Ask direct questions about self-pay and written payment plans. If there's a gap, use structured financing carefully. Gather your documents before you call. Keep enough stability in place for life after discharge.
That's how people move from panic to admission.
For local families, it also helps to talk with a real treatment team instead of trying to stitch together answers from search results. A confidential conversation can tell you very quickly whether detox, residential treatment, or IOP makes the most sense, and what the first financial step should be.
Addiction Resource Center is a TRICARE West Region network provider through TriWest Healthcare Alliance for adult substance use disorder intensive outpatient and partial hospitalization treatment. TRICARE referral and prior authorization requirements depend on your plan. Network participation does not imply endorsement by the Department of Defense or the Defense Health Agency.
Cost should be addressed early. It should not be the reason you stop.
The conversation is confidential, straightforward, and focused on helping you or your loved one take the next step without guessing.
Learn more about our outpatient addiction treatment services, or contact Addiction Resource Center.
Talk with us
Addiction Resource Center offers intensive outpatient treatment (IOP) for adults 18+ at our Yuba City office or by telehealth. If you need detox or residential care first, we coordinate it with our partner, Ona Treatment Center in Browns Valley, CA. Call or text 530-625-7910.
Check my insurance